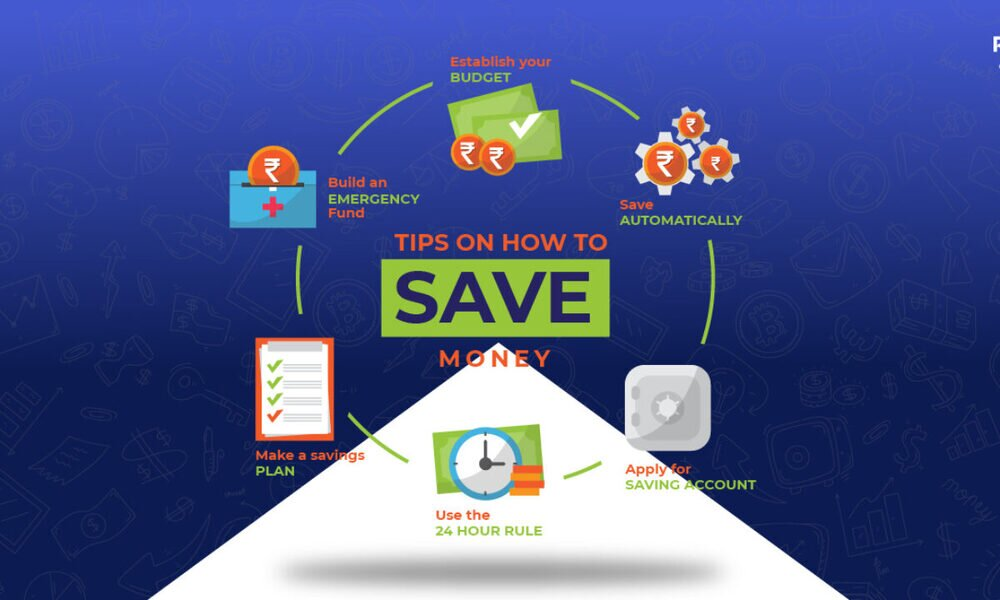
Money has a quiet, sneaky way of vanishing. You start the month with a fresh paycheck and every intention of being responsible, but as the days roll on, reality takes over. A daily coffee run, a couple of late-night food delivery orders, a streaming subscription you forgot to cancel after the trial ended—and suddenly, your bank account looks surprisingly empty.
The most frustrating part? You rarely have anything major to show for it. You didn’t buy a new car or fly off on a lavish vacation, yet your hard-earned income seemed to evaporate into thin air.
When people finally decide to fix their finances, they usually jump to extremes. They promise to stop going out completely, cook every single meal at home, cut out all non-essential fun, and save half their income starting immediately. But extreme financial restriction works about as well as a strict crash diet: you last a week or two, get burned out, and end up on a guilt-driven shopping spree.
Building real wealth isn’t about miserable sacrifice or maintaining complicated spreadsheets. It comes down to intentional awareness. By tweaking how you handle everyday choices and making small, regular adjustments, you can keep significantly more of your money—without feeling like you’re missing out on life.
Why Saving Every Month Changes Everything

Saving money isn’t just about accumulating numbers in an app. It’s about buying your future self clarity, options, and peace of mind.
       NO CASH RESERVES                       WITH A FINANCIAL BUFFER
┌───────────────────────┐              ┌───────────────────────┐
│ Unexpected Expense    │              │ Unexpected Expense    │
└───────────┬───────────┘              └───────────┬───────────┘
            │                                      │
            ▼                                      ▼
┌───────────────────────┐              ┌───────────────────────┐
│ Stress, Panic, Debt   │              │ Handled with Ease     │
└───────────────────────┘              └───────────────────────┘
When you live paycheck to paycheck, even a small hiccup—a flat tire, a dental emergency, or a sudden dip in freelance client work—becomes a full-blown crisis. Having a dedicated cash reserve transforms potential emergencies into minor inconveniences.
Beyond handling unexpected expenses, regular savings give you real choices. They allow you to:
- Step away from toxic situations: Leaving an unhealthy work environment or a bad living arrangement is far easier when you have financial room to breathe.
- Act on real opportunities: Whether it’s enrolling in an advanced course, starting a passion project, or taking a spontaneous trip, having accessible savings lets you say yes when opportunities arrive.
- Remove daily financial anxiety: The constant mental strain of worrying if a card will decline takes a genuine toll. Financial stability buys quiet mental peace.
Step 1: Track Down Your Invisible Cash Leaks
Before you design a working budget, you need an accurate picture of where your money currently goes. Most people think they know their spending, but reality often tells a very different story.
For the next 30 days, make it a point to log every single expense. You don’t need fancy software—a simple phone note, a plain physical journal, or a basic spreadsheet is plenty. Group your spending into four clear categories:
- Fixed Needs: Rent or mortgage, basic utility bills, loan repayments.
- Variable Essentials: Groceries, transportation, essential health items.
- Flexible Wants: Dining out, coffee shops, entertainment, social events.
- Recurring Micro-Expenses: Subscriptions, app memberships, cloud storage plans.
+-----------------------------------------------------------------------------------+
|                           THE DAILY SPENDING EFFECT                               |
+----------------------+-----------------------+------------------------------------+
| Unnoticed Daily Item | Typical Item Cost     | Monthly Financial Impact           |
+----------------------+-----------------------+------------------------------------+
| Daily Café Coffee    | $5.50 / day           | ~$165.00 / month                   |
| Unused App Subscriptions| $12.00 / app         | ~$36.00 / month (3 apps)           |
| Frequent Food Delivery| $18.00 in fees/markups| ~$144.00 / month (2x week)         |
| Unplanned Online Purchases| $25.00 / week      | ~$100.00 / month                   |
+----------------------+-----------------------+------------------------------------+
| TOTAL POTENTIAL SAVINGS:                      | ~$445.00 / month ($5,340 / year)   |
+----------------------------------------------+------------------------------------+
When you look back at your tracked expenses, pay close attention to frictionless, low-cost purchases. That $5 coffee or $15 delivery fee doesn’t feel significant in the moment, but together, these minor items quietly siphon off hundreds of dollars every month.
Step 2: Set Up a Simple, Low-Friction Budget

The word “budget” often sounds restrictive, but a good budget is simply a roadmap that gives your money clear purpose. If your budgeting framework is overly complex, you’ll likely abandon it within a few weeks.
A reliable, beginner-friendly model to try is the 50/30/20 Framework:
                   ┌─────────────────────────────────────────┐
                   │        THE 50 / 30 / 20 FRAMEWORK        │
                   └────────────────────┬────────────────────┘
                                        │
         ┌──────────────────────────────┼──────────────────────────────┐
         ▼                              ▼                              ▼
┌──────────────────┐           ┌──────────────────┐           ┌──────────────────┐
│  50% NEEDS       │           │  30% WANTS       │           │  20% SAVINGS     │
├──────────────────┤           ├──────────────────┤           ├──────────────────┤
│ • Rent / Mortgage│           │ • Dining Out     │           │ • Emergency Fund │
│ • Utilities      │           │ • Hobbies        │           │ • Investments    │
│ • Basic Groceries│           │ • Entertainment  │           │ • Debt Payoff    │
│ • Transport      │           │ • Vacations      │           │ • Future Goals   │
└──────────────────┘           └──────────────────┘           └──────────────────┘
- 50% for Needs: Necessary living costs that you cannot easily eliminate.
- 30% for Wants: Choices that bring fun, comfort, and entertainment to your life.
- 20% for Savings & Debt Reduction: Funds directed toward building an emergency cushion, investing, or eliminating debt balances.
If fixed expenses currently take up more than 50% of your take-home pay—which is common in high-cost areas—don’t sweat it. Simply tweak the numbers to match your reality. The primary goal is establishing intentional boundaries for your cash.
Step 3: Put a Pause on Impulse Buying
Online shopping is systematically engineered to eliminate friction between wanting an item and buying it. Saved payment details and single-click ordering make it remarkably easy to spend money without thinking twice.
To break impulse habits, introduce deliberate delays into your checkout routine:
- The 48-Hour Delay for Small Purchases: When you spot something non-essential online, add it to your cart and walk away for two full days. If you still feel it adds genuine value to your life after 48 hours, reconsider buying it. More often than not, the urge completely disappears.
- The 30-Day Rule for Big-Ticket Items: For significant expenses, mandate a 30-day waiting period. Use that window to research alternatives, read long-term customer reviews, and confirm the purchase aligns with your true priorities.
- Delete Stored Credit Card Details: Remove saved credit cards from your web browser and retail apps. Forcing yourself to physically get up, grab your wallet, and type in card numbers creates just enough friction for your brain to evaluate if you truly need the item.
Step 4: Run a Periodic Subscription Checkup
Subscription business models rely heavily on human neglect. Companies know that once an automated monthly charge begins, most customers will keep paying long after they stop actively using the service.
Every three to six months, perform a quick subscription checkup:
Step 1: Review your last 3 bank and credit card statements.
                             │
                             ▼
Step 2: Highlight recurring monthly charges (apps, streaming, memberships).
                             │
                             ▼
Step 3: Ask: "Have I actively used this in the last 30 days?"
                             │
            ┌────────────────┴────────────────┐
            ▼                                 ▼
         [ YES ]                           [ NO ]
  Keep within budget.              Cancel immediately.
If you are on the fence about keeping a streaming channel or specialized app, cancel it anyway. If you genuinely miss it a couple of weeks later, you can always renew. In most cases, you won’t even notice its absence.
Step 5: Lower Food and Grocery Costs
Food is usually one of the most adjustable lines in a monthly budget, making it an ideal place to unlock quick, meaningful savings.
Grocery Shopping with Strategy
- Check the Pantry First: Before making a grocery run, inspect your fridge and pantry. Plan your upcoming meals around ingredients you already have to minimize food waste.
- Don’t Shop on an Empty Stomach: Shopping while hungry leads directly to impulse buys, especially in the snack and ready-to-eat sections.
- Opt for Store Brands: Generic or private-label staples (like oats, canned goods, spices, and frozen produce) offer identical quality to big name brands at a 20% to 30% discount.
Rethinking Takeout and Restaurants
Dining out and catching up over food with friends is great, but relying on food delivery apps as a default for weeknight dinners drains funds fast.
Instead of cutting out restaurants entirely, treat dining out as a planned social event rather than a routine convenience. Cooking quick, batch-prepared meals during the busy workweek saves delivery charges for occasions when you really want to enjoy them.
Step 6: Put Your Savings on Autopilot

The single biggest mistake people make with saving is waiting until the end of the month to put away whatever happens to be left over. Unsurprisingly, whatever money sits in a primary checking account usually finds a way to get spent.
Flip this dynamic around by adopting the “Pay Yourself First” habit.
                     ┌──────────────────────────────┐
                     │     INCOME ARRIVES IN        │
                     │     CHECKING ACCOUNT         │
                     └──────────────┬───────────────┘
                                    │
                                    ▼
                     ┌──────────────────────────────┐
                     │   AUTOMATIC INSTANT TRANSFER │
                     └──────────────┬───────────────┘
                                    │
         ┌──────────────────────────┴──────────────────────────┐
         ▼                                                     ▼
┌──────────────────────────────┐                      ┌──────────────────────────────┐
│     SAVINGS ACCOUNT          │                      │  REMAINING CHECKING BALANCE  │
│  (Emergency Fund / Goals)    │                      │   (Safe for Everyday Living) │
└──────────────────────────────┘                      └──────────────────────────────┘
Set up an automated recurring transfer with your bank so that a defined portion of your income moves into a separate savings account the moment you get paid.
When you automate savings, your day-to-day spending naturally adjusts to the remaining balance in your checking account. Saving transforms from a stressful afterthought into a seamless, automatic routine.
Step 7: Establish an Emergency Safety Net
An emergency cushion is the absolute foundation of long-term financial stability. Without one, any sudden real-world surprise can push you toward high-interest debt, undoing months of hard work.
How Much Cash Should You Keep?
- Initial Emergency Target: Aim for $1,000 to $1,500 as quickly as you reasonably can. This protects you against routine surprises like basic car repairs or unexpected medical copays.
- Full Financial Cushion: Build up to 3 to 6 months’ worth of core living costs. This provides serious protection against job changes, extended illness, or major life transitions.
Keep emergency reserves in a separate High-Yield Savings Account (HYSA). This ensures your money stays out of sight from daily spending temptations while earning a competitive interest rate to keep pace with inflation.
Common Spending Traps to Watch For
As you refine your approach to money, keep an eye out for these classic financial pitfalls:
- Falling for “Discount” Logic: Buying an item on sale for $70 down from $100 isn’t saving $30—it’s still spending $70 on something you might not have wanted in the first place.
- Lifestyle Inflation: As your career progresses and income grows, it’s easy to let spending expand right alongside it. Whenever you earn a raise or bonus, try to route a portion of that new income directly into savings before expanding your lifestyle.
- Over-focusing on Micro-Expenses: Trimming tiny pleasures while ignoring high-interest credit card debt or an overpriced car payment won’t yield big results. Address high-impact financial expenses first.
- Comparing Finances to Others: Social media shows carefully selected highlight reels. Trying to match the visible lifestyle of friends or colleagues often leads to hidden debt and unnecessary pressure.
Final Thoughts: Aim for Consistency Over Perfection
Building healthy financial habits isn’t about maintaining strict frugal perfection every single day. You don’t need to eliminate all discretionary fun or feel guilty about buying items that bring you genuine joy.
The main goal is simply aligning your daily spending with what actually matters to you. By paring back on minor, low-value purchases, you free up cash for what truly counts—whether that’s paying off debt, building real emergency protection, or funding big long-term dreams.
Start small. Pick one or two practical adjustments from this guide—like tracking your spending for a month or scheduling an automatic savings transfer—and build momentum from there. Over time, those steady, manageable actions add up to complete financial control.
FAQs
How soon will I notice a real difference after I start tracking my daily spending?
Most people spot sneaky cash leaks within the first two weeks, which naturally slows down impulsive buys almost right away.
What if my essential bills naturally take up more than half of my monthly paycheck?
Simply adjust the ratios to fit your reality—like trying a 60/20/20 split—or focus on trimming small flexible costs while finding ways to boost your income.
Where is the safest, smartest place to park my emergency savings reserve?
Keep your emergency cash in a separate High-Yield Savings Account so it stays out of daily spending reach while quietly earning interest.
Should I clear all my debts before I start putting money into savings?
Build a quick $1,000 starter emergency buffer first to handle sudden surprises, then throw extra cash at high-interest credit cards or loans.